Tag: faith

  • John Jacob Astor: The Founder Who Built a Fortune That Outlasted Everyone Else’s

    John Jacob Astor: The Founder Who Built a Fortune That Outlasted Everyone Else’s

    In 1783, a young man arrived in New York with almost nothing to his name. He’d been born Johann Jakob Astor, the son of a butcher in the small German town of Walldorf, and he came to America with little more than a few flutes he hoped to sell. By the time he died sixty-five years later, John Jacob Astor was the richest man in the United States, and the rule he built into his will would go on to protect his family’s fortune longer than almost any other in American history.

    From Flutes to a Fur Empire

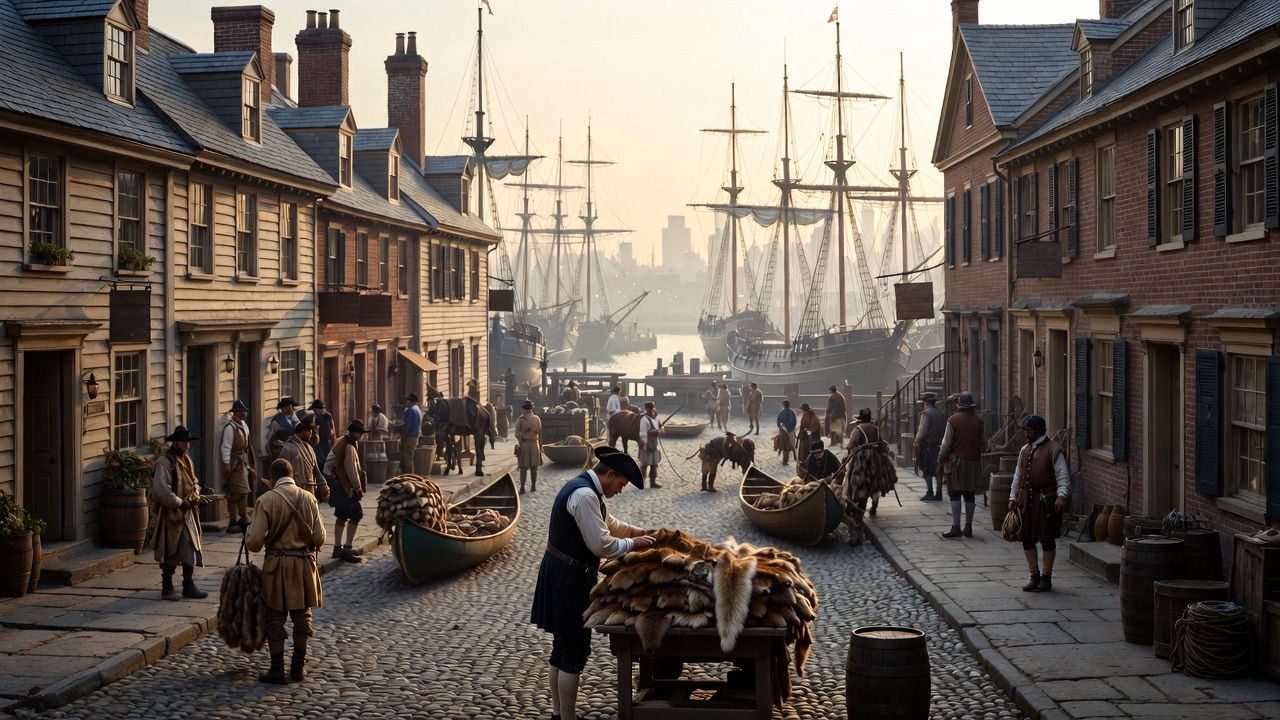
    Astor’s first real business wasn’t glamorous: buying furs from trappers and Native traders, then selling them at a markup. But he was relentless and shrewd, and by 1808 he’d founded the American Fur Company, aggressively building toward a genuine monopoly on the fur trade across huge stretches of the American frontier. It’s worth being honest about the less admirable part of how that fortune grew, too: starting around 1800, Astor also exported opium into China, one of several American and British merchants doing the same. China’s own government had banned opium imports since 1729, so this trade was, by China’s law, smuggling, carried out through small boats that met his ships offshore to avoid the ports. It was not, however, illegal or scandalous by the standards of Astor’s own country at the time; Western merchants conducted the trade fairly openly, and it didn’t damage a single reputation back home, including his. That doesn’t erase the real harm it caused. It just means Astor wasn’t crossing a line his own contemporaries recognized as wrong; he was participating in something the West hadn’t yet reckoned with, decades before it exploded into the Opium Wars.

    John Jacob Astor looking over land that would become New York City, from open farmland to the modern Manhattan skyline

    The Real Genius: Knowing Where a City Was Headed

    Astor’s most important decision wasn’t in furs at all. As New York City’s population began to explode in the early 1800s, he started quietly buying up undeveloped land and vacant lots on the edges of the city, land nobody else wanted yet because it wasn’t worth much yet. He was betting, correctly, that the city would keep growing north, and that the empty fields he was buying cheaply would eventually sit in the middle of some of the most valuable real estate on earth. He was right. By the time he died in 1848, his estate was worth an estimated $20 million, an almost unimaginable sum for the era, built substantially on land he’d bought decades earlier for a fraction of what it eventually became worth.

    The Rule That Protected the Fortune

    Most wealthy men of Astor’s era left their fortune to their children outright, and hoped for the best. Astor did something different. He built a rule into his will: half of what he had would go directly to his grandchildren, not his own children, and he required his children to follow the same rule with their own money when their turn came. It’s a strategy known today as a generation-skipping structure, and the idea behind it is simple but powerful: no single generation, however careless or generous, could ever spend the whole fortune, because half of it was always protected, already promised to the generation after them before they ever got the chance to touch it.

    Astor also made a second, less structural but equally deliberate choice about who within his own generation would actually be trusted with the bulk of it. His eldest son, also named John Jacob, was widely regarded by the family as unable to manage a fortune of this size. Rather than defaulting to birth order, Astor directed the majority of his estate to his second son, William, who had already spent years proving himself inside the family business. We’ll dig into exactly how that decision played out, and what William did with it, in its own dedicated piece.

    That rule held for well over a hundred years, generation after generation, longer than almost any comparable fortune of the era managed to stay intact. We’ll come back to exactly how, and why, it finally ended, much later than you might expect, and for a reason that had nothing to do with anyone breaking the rule on purpose.

    Not far away, at roughly the same time Astor was building his real estate empire, a young man was doing pretty well for himself running a small ferry boat around New York harbor. His name was Cornelius.

    What This Actually Teaches

    Jeremiah 17:11 offers a real warning worth sitting with here: “Like a partridge that hatches eggs it did not lay is the man who gains riches by unjust means; when his life is half gone, they will desert him, and in the end he will prove to be a fool.” (NIV) Astor’s story doesn’t fit that warning neatly, and that’s exactly what makes it worth thinking through honestly. Real vision and real discipline built the bulk of his fortune, buying land nobody else understood the value of yet, then protecting it with a structure smarter than almost anyone else built at the time. Part of it also came from a trade that caused real, lasting harm, even though it wasn’t considered wrong by the people around him at the time. That’s worth sitting with rather than resolving too quickly: a clean conscience in your own era doesn’t always mean a clean legacy, and wisdom by the standards of one’s own time isn’t the same as wisdom by God’s.

    The rule he left behind, though, is worth its own honest credit. Astor didn’t just build wealth. He built a structure designed to outlast his own choices, and even the choices of his children. That’s a different kind of stewardship than simply being rich, planning specifically for people who hadn’t been born yet.

    This content is for educational purposes only and is not personalized financial, legal, or tax advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading


    Part of Our Astors Series

    Astor Series Spinoffs

    • Is HBO’s The Gilded Age Based on a True Story? Caroline Astor’s Real History — Coming Nov 5
    • How the Astors Chose Their Heir: Skipping the Firstborn for the Son Who Could Grow the Money — Coming Nov 12
    • The Rule That Finally Broke: How the Astor Trust Structure Actually Ended — Coming Nov 19
    • Peacock Alley: How a Family Feud Accidentally Invented Modern Luxury Hospitality — Coming Nov 26
    • The Scandal That Put Them on the Titanic — Coming Dec 3

    📖 Enjoy stories like this? Check out The Vanderbilts: Empire, Excess, Loss, and Redemption — available now →
  • Is It a Sin to Gamble? A Biblical Look

    Is It a Sin to Gamble? A Biblical Look

    Gambling isn’t named directly anywhere in Scripture, since the modern casino and lottery industry didn’t exist in the ancient world. But several principles Scripture does address speak directly to what gambling actually involves, and most point in a cautionary direction. This is worth reading alongside a related question we’ve tackled separately: is investing in the stock market itself a form of gambling?

    Getting Rich Quick, Directly Addressed

    Proverbs 13:11 says, “Dishonest money dwindles away, but whoever gathers money little by little makes it grow.” (NIV) Gambling is built entirely around the opposite instinct: a large, quick, chance-based outcome rather than steady, deliberate stewardship. Proverbs 28:20 adds a further warning: “One eager to get rich will not go unpunished.” (NIV) These aren’t verses about gambling by name, but they describe precisely the mindset gambling is designed to activate.

    The Math Behind It

    Every form of gambling, by design, has a built-in house edge, meaning the system is structured so that, over time, the house wins and the player loses. This is a meaningful distinction from investing, where risk is taken in exchange for a share in real, productive economic activity. Gambling creates no value, it simply moves money from many losers to a few winners, with the house guaranteed a cut regardless of outcome.

    A Real Tax on the Poor

    Here’s where the honest math gets genuinely hard to look at. State lotteries specifically have earned a real, well-documented nickname: “a tax on the poor.” It’s not a rhetorical exaggeration. An Economist analysis of public lottery records found that adults in the poorest 1% of U.S. zip codes spend an average of nearly 5% of their income, roughly $600 a year, on lottery tickets alone. Adults in the wealthiest 1% of zip codes spend just 0.15% of their income, about $150 a year, on the same tickets. That’s a 33-times difference in the share of income spent on the exact same product. A separate Bankrate study found a similar pattern: the lowest-income households spend an average of $412 a year on lottery tickets, nearly four times the $105 spent by the highest earners, despite the highest earners making more than eight times as much money.

    Research published by the National Bureau of Economic Research adds a further, sobering detail: lottery spending doesn’t come from disposable income sitting on the side. It measurably crowds out other household spending, with the reduction proportionally larger among low-income households specifically, meaning the money is coming directly out of budgets that had less room to give in the first place.

    What That Same Money Could Have Become

    Take that $600-a-year figure and run it the other direction. If, instead of lottery tickets, that same $600 a year had gone into a simple S&P 500 index fund earning the market’s long-term historical average of roughly 10% annually:

    10 Years20 Years30 Years
    Total contributed$6,000$12,000$18,000
    Value if invested instead$9,562$34,365$98,696

    That same modest, ordinary amount of money, the kind that can genuinely feel insignificant one ticket at a time, becomes nearly $100,000 over 30 years simply by changing where it goes. Even using the more conservative Bankrate figure of $412 a year, the same 30-year period turns roughly $12,360 in contributions into approximately $67,772. Neither of these numbers requires a windfall, a lucky number, or a jackpot. They require nothing more than consistency and time, the two things a lottery ticket is specifically designed to make feel unnecessary.

    Stewardship, Not Just Legality

    Something being legal has never been the same question as something being wise stewardship. 1 Corinthians 10:23 offers a useful lens: “‘I have the right to do anything,’ you say, but not everything is beneficial.” (NIV) Whether or not gambling is a sin in every individual instance, the honest math and the underlying heart posture it tends to encourage, chasing a windfall rather than diligent, faithful stewardship, are both worth taking seriously. The numbers above make that math concrete rather than abstract, especially for households with the least room to absorb the loss.

    Where This Leaves You

    Scripture doesn’t hand down a verse-by-verse verdict on gambling specifically. But the principles it does offer, patient stewardship over quick riches, honest value creation over house-edge extraction, and wisdom over mere legality, point in a clear, cautionary direction. The real-world data on who actually funds state lotteries, and what that same money could have become instead, only sharpens that direction further.

    This content is for educational purposes only and is not personalized financial advice. Past market performance does not guarantee future results. If gambling has become a struggle you can’t control on your own, the National Problem Gambling Helpline (1-800-522-4700) offers free, confidential support. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • 6 Signs Your Church’s Approach to Giving May Be Unhealthy

    6 Signs Your Church’s Approach to Giving May Be Unhealthy

    Most unhealthy approaches to giving aren’t extreme or obvious. They’re common, subtle, and easy to sit through without ever naming what’s happening. Here are 6 signs worth knowing, each measured against what Scripture actually says.

    1. Giving Is Tied to a Financial Blessing Promise

    “Give, and God will make you prosper financially” goes beyond what Scripture promises. Paul’s actual standard is simpler: “Each of you should give what you have decided in your heart to give, not reluctantly or under compulsion, for God loves a cheerful giver” (2 Corinthians 9:7, NIV). Cheerful, willing giving, not a financial transaction with God, is the standard.

    2. Not Giving Is Framed as Inviting a Curse

    This pattern usually leans on Malachi 3:8-10, a passage originally addressed to Israel’s priests about a specific covenant obligation, applied instead as a general threat to any Christian who doesn’t give. It also skips over Galatians 3:13, which teaches that believers in Christ have been redeemed from a curse-based system entirely.

    3. Guilt-Trip Appeals Equate Love for God With the Amount Given

    “If you really loved God, you’d give more” is the direct opposite of “not reluctantly or under compulsion” (2 Corinthians 9:7, NIV). Love for God and generosity are connected, but generosity used as proof of love, measured by a dollar amount, turns worship into a performance.

    4. Appeals Rely on In-the-Moment Emotional Pressure

    Paul’s language is that each person gives “as he has purposed in his heart” (2 Corinthians 9:7) — decided ahead of time, prayerfully, not decided in the pressure of the moment an appeal is being made.

    5. Giving Is Expected, but Financial Reporting Is Vague or Hidden

    Paul modeled the opposite. He deliberately structured how the Jerusalem collection was handled so that no one could question the church’s integrity with the money (2 Corinthians 8:20-21). A church that asks for sacrificial giving while staying vague about where it goes isn’t following that example.

    6. Giving Level Affects Standing, Voice, or Membership

    In Acts 5:1-4, Ananias and Sapphira weren’t judged for giving less. Peter tells them directly the money was theirs to keep or give, either way, before it was ever given. The sin was the lie about what they gave, not the amount itself. Giving in the early church was consistently voluntary, never a condition of belonging.

    This content is for educational purposes and reflects general biblical principles, not a judgment of any specific church. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • Should Christians Care About Their Credit Score?

    Should Christians Care About Their Credit Score?

    A credit score measures something Scripture genuinely does care about, whether you can be trusted to do what you said you’d do, even though the Bible obviously never mentions the concept directly. Whether that means you should actively pursue a high score is where thoughtful Christian voices actually disagree, and it’s worth knowing since it directly affects real decisions later, like whether refinancing a mortgage actually makes sense for you.

    What a Credit Score Actually Measures

    A credit score is a numerical summary of borrowing history: whether payments were made on time, how much available credit is being used, and how long accounts have been open. It’s not a measure of income, savings, or net worth. It’s specifically a measure of repayment reliability.

    One Well-Known View: Ignore It Entirely

    Dave Ramsey, one of the most influential voices in Christian personal finance, has taken a famously hard line on this. In a widely shared statement, he described a credit score as simply an I love debt rating, arguing it measures nothing about actual financial health, only how much you’ve borrowed and repaid. Ramsey has gone further, telling followers that having no credit score at all, a score of zero, is a genuinely good outcome, not a problem to fix.

    The Pushback From Other Financial Voices

    Plenty of financial professionals, including some who share Ramsey’s broader debt-averse philosophy, push back specifically on the credit-score-of-zero advice. In practice, a credit check affects far more than loan approval: utility deposits, cell phone plans, apartment rental applications, auto insurance rates, and sometimes even job applications all commonly reference credit history. Having no score at all, rather than a low one, can make basic parts of daily life measurably harder, not easier.

    What Scripture Actually Speaks To

    Scripture doesn’t weigh in on FICO scores, but it does weigh in on reputation and trustworthiness directly. Proverbs 22:1 says, “A good name is more desirable than great riches; to be esteemed is better than silver or gold.” (NIV) A credit score, imperfectly and narrowly, is one modern proxy for a very old idea: whether your word and your follow-through can be relied on.

    Where This Actually Goes Wrong

    The real danger isn’t caring about your credit score. It’s chasing the number itself, taking on debt specifically to improve it, treating a high score as an achievement worth pursuing for its own sake, rather than as a natural byproduct of consistent, honest financial behavior. That’s where the Ramsey critique has real teeth: a credit score can start to feel like a scoreboard for something that was never supposed to be a game.

    Where This Leaves Us

    You don’t have to choose between Ramsey’s ignore-it-entirely camp and a maximize-the-number mindset. A middle path exists, and it’s probably the most common one in practice: pay everything on time, keep debt modest and purposeful rather than something pursued to build a score, and let the credit score be a quiet byproduct of faithfulness rather than a goal in itself. Whatever number results from that is genuinely secondary to the character it reflects.

    This content is for educational purposes only and is not personalized financial advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • What the Vanderbilts Teach Us About Assets vs. Options

    What the Vanderbilts Teach Us About Assets vs. Options

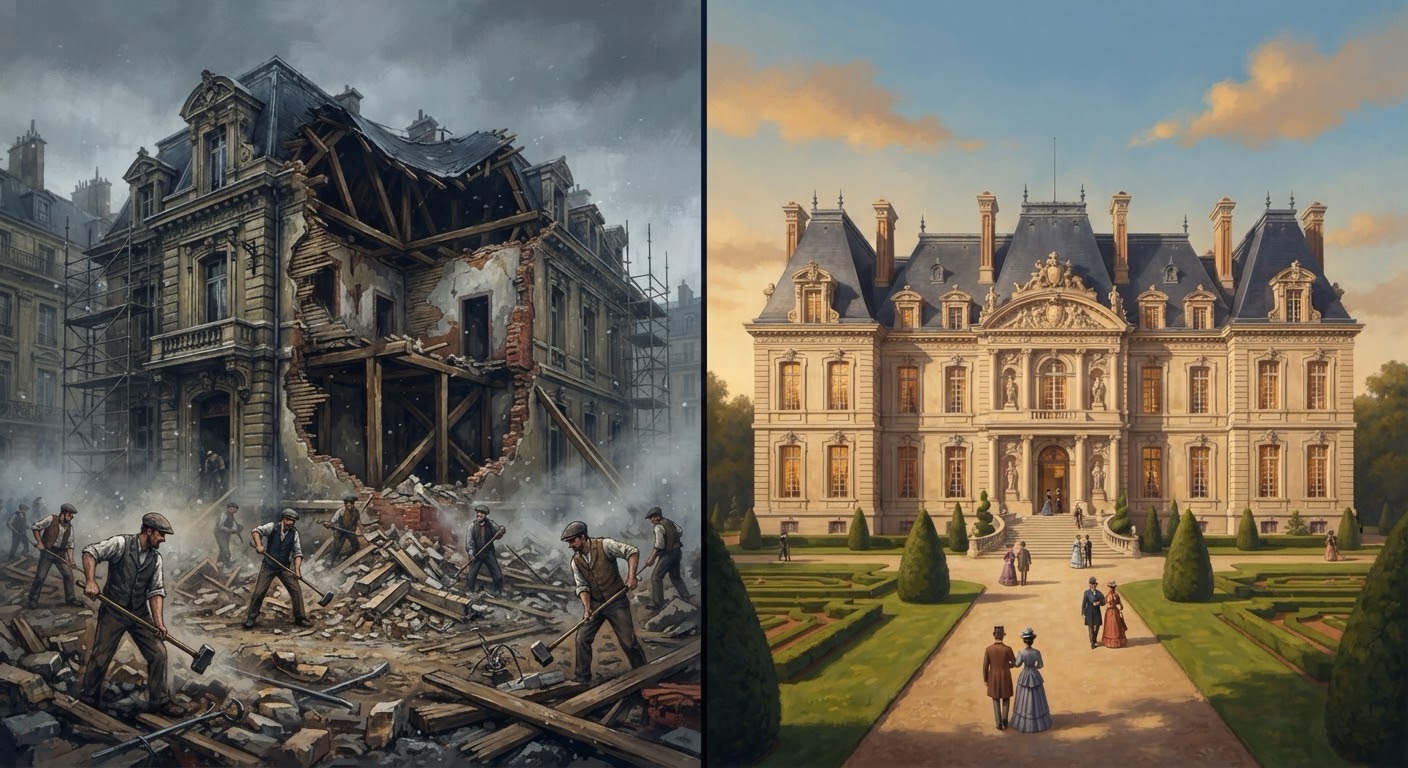
    Here’s the sharpest comparison the whole Vanderbilt story offers. The Fifth Avenue mansions and the Newport “cottages” were pure consumption, and the moment the money behind them ran out, they were gone, literally demolished in some cases, by 1947. Biltmore lost roughly $250,000 a year for three decades straight. It’s still standing today, generating over $250 million annually.

    Split image contrasting a Fifth Avenue mansion mid-demolition against the Biltmore chateau standing intact and thriving

    The difference between those two outcomes isn’t really about which building was nicer. It’s about the difference between an asset and a liability that simply never gets converted back into anything useful.

    Assets Equip the Next Generation in Ways Money Alone Doesn’t

    Biltmore didn’t just sit there as a line item on a balance sheet. Because it was a real, physical, structural thing, it forced the generations that inherited it into real, hands-on stewardship, land management, hospitality operations, eventually a working winery. None of that would have happened if the inheritance had simply been a check. The asset itself created the demand for the skill.

    Workers harvesting grapes across Biltmore's vineyard rows with the chateau visible on the hill behind them

    Education and Habits Are What Actually Determine the Outcome

    The mansions taught the generations that inherited them how to spend. Biltmore, out of sheer necessity once it stopped being profitable, taught the generation that inherited it how to manage. The asset itself didn’t determine which direction the family went. What the family was forced to learn in order to hold onto it did. This is worth connecting to a distinction we’ve made elsewhere: what actually counts as an asset often has less to do with the object itself and more to do with whether it’s actively put to work.

    A Method to the Madness

    It’s worth revisiting the Commodore’s succession approach with this specific lens. Concentrating the estate in one heir rather than splitting it evenly looked, at the time, like it might have simply been favoritism or bluntness. Laid next to what happened once later generations abandoned that same discipline, a different reading becomes hard to ignore: the Commodore’s instincts weren’t cruelty. They may have functioned as an asset in their own right.

    What Scripture Adds

    Ecclesiastes 11:1-2 offers a genuinely practical principle here: “Ship your grain across the sea, and in time, profits will flow back to you. Invest in seven ventures, yes, in eight; you do not know what disaster may come upon the land.” (NIV) The instruction isn’t simply “acquire things.” It’s “put resources into motion, diversified, active, working,” precisely the difference between Biltmore’s decades of forced active management and the mansions’ passive, purely decorative existence right up until the money to sustain them disappeared.

    Where This Leaves You

    Leaving heirs cash and an established lifestyle tends to leave them with nothing once both are spent. Leaving heirs real, structural assets, even ones that lose money for decades, tends to leave them with options, and options are what let a family recover from thirty years of loss instead of simply disappearing along with it.

    This content is for educational purposes only and is not personalized financial or estate planning advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    This post is part of our ongoing look at lessons from the Vanderbilt series. Start the full story from the beginning here.

  • What Does the Bible Say About Worry Over Money?

    What Does the Bible Say About Worry Over Money?

    Jesus addresses financial worry directly and repeatedly, and His core instruction is consistent: worry doesn’t add anything productive, and it reflects a deeper question of where trust is actually placed. Practical preparation, like building a real emergency fund, is a genuinely faithful response to that same underlying concern.

    Jesus’s Direct Teaching

    Matthew 6:25-34 is the clearest, most extended teaching on this in Scripture. Jesus points to birds, who don’t store up crops in barns, and wildflowers, more beautifully clothed than Solomon at his wealthiest, and asks: if God cares for these, will He not care for you? He states plainly, “Who of you by worrying can add a single hour to your life?” (NIV) Worry, in this teaching, isn’t just unpleasant, it’s genuinely unproductive, adding nothing to the actual outcome.

    What This Doesn’t Mean

    This isn’t a command against planning, budgeting, or working diligently. Proverbs repeatedly commends preparation and diligence. The teaching targets anxiety, a corrosive, trust-eroding worry, not responsible foresight. Someone can budget carefully and plan for the future while still fully trusting God, and someone can refuse to plan at all while being consumed by exactly the anxiety Jesus warns against.

    The Alternative Jesus Offers

    Philippians 4:6-7 gives the practical alternative: “Do not be anxious about anything, but in every situation, by prayer and petition, with thanksgiving, present your requests to God.” (NIV) The instruction isn’t simply “stop worrying.” It’s a redirection, taking the specific concern and bringing it honestly to God rather than carrying it alone.

    Where This Leaves You

    Financial worry is addressed head-on in Scripture, not dismissed as unimportant, but treated as a real, common struggle with a real, specific answer: bring it to God directly, trust His provision, and keep planning and working diligently in the meantime. Those two things were never meant to be in conflict.

    This content is for educational purposes only and is not personalized financial advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • Why Pastors Go Silent on Giving — And Why That’s Not Actually Safer

    Why Pastors Go Silent on Giving — And Why That’s Not Actually Safer

    Silence on giving feels safer than manipulation, but it isn’t actually safe. It just trades one problem for another: a congregation that’s never been taught a biblical view of money at all.

    The Reasonable Fear Behind the Silence

    Most pastors who go quiet on giving aren’t lazy or uncaring. They’ve seen the damage guilt-driven, manipulative preaching on tithing can do, and they don’t want any part of it. That’s a good instinct. But avoiding the topic entirely doesn’t protect a church from the problem, it just creates a different one: a congregation left to figure out biblical stewardship on their own, usually from culture instead of Scripture.

    Silence Has a Cost Too

    Scripture doesn’t treat teaching on money as optional or dangerous territory to avoid. Jesus talked about money constantly, more than almost any other subject. Paul spent two full chapters (2 Corinthians 8-9) carefully, directly asking the Corinthian church to give generously to a specific need. He wasn’t silent, and he wasn’t manipulative either. He modeled something in between: clear, direct teaching, held together with real transparency and respect for people’s freedom to decide.

    When pastors stay silent, churches often end up under-resourced for real ministry, and members never learn what Scripture actually teaches about generosity, stewardship, or contentment. The absence of manipulation isn’t the same thing as the presence of health.

    What This Series Explores

    The rest of this series walks through both ends of this spectrum: the signs that a church’s approach to giving has become unhealthy, the signs that it’s genuinely healthy, and practical, biblical ways pastors can challenge their people to give without falling into either silence or manipulation.

    Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • Is It Biblical to Negotiate Medical Debt or Settle for Less Than You Owe?

    Is It Biblical to Negotiate Medical Debt or Settle for Less Than You Owe?

    Negotiating a medical bill down, or settling it for less than the original amount, is not the same as refusing to pay a debt. Scripture takes honoring debt seriously, but it also has real precedent for structured relief when a debt becomes genuinely unbearable. This is exactly the kind of unexpected expense an emergency fund is meant to absorb, though many people are facing this reality without one already in place.

    A Real, Growing Problem

    According to Kaiser Family Foundation (KFF) national surveys, about 41% of U.S. adults currently carry some form of medical or dental debt, whether it’s on a credit card, in a payment plan, owed directly to family, or headed to collections. It’s a uniquely difficult category of debt: it’s rarely voluntary, it’s often incurred during a genuine emergency, and the initial billed amount frequently has little relationship to what insurers or the hospital itself would actually accept. Hospitals routinely negotiate their own rates with insurance companies, which means the sticker price handed to an uninsured or underinsured patient is often not a fixed, non-negotiable number at all.

    The Biblical Precedent for Debt Relief

    Scripture doesn’t treat debt relief as a foreign concept. Deuteronomy 15:1-2 establishes the Sabbatical year: “At the end of every seven years you must cancel debts… every creditor shall cancel any loan they have made to a fellow Israelite.” (NIV) This wasn’t a suggestion for the exceptionally generous, it was a structured, expected part of how the community managed debt. God built a rhythm of relief directly into the economic life of his people, not as an exception to good stewardship, but as part of it.

    Negotiating in Good Faith vs. Avoiding a Debt

    There’s a meaningful difference between the two postures worth being honest about. Negotiating in good faith means being transparent about your actual financial situation, communicating directly rather than going silent, and following through on whatever payment plan or settlement is agreed to. Avoiding a debt means ignoring it, hoping it disappears, or being dishonest about your ability to pay. The first is a reasonable, even wise, response to a genuinely difficult situation. The second is the kind of behavior Scripture consistently warns against.

    Mercy Runs Both Directions

    It’s worth noting that hospitals and billing departments are not automatically the villain in this picture either. Many have real financial assistance programs, charity care policies required of nonprofit hospitals, and structured negotiation processes built specifically for situations like this, and using them isn’t manipulation, it’s using the system as it was actually designed to work. Recent regulatory changes have also removed many smaller medical collection accounts from credit reports entirely, a meaningful, if partial, acknowledgment that this category of debt deserves different treatment than ordinary consumer debt. Mercy in this scenario isn’t just something the debtor hopes to receive. It’s often something already built into the system, waiting for someone to simply ask.

    Where This Leaves Us

    If you’re facing medical debt that feels impossible, negotiating it honestly, requesting an itemized bill, asking about financial assistance programs, or proposing a realistic payment plan, is not a failure of faith or integrity. It’s stewardship under real, often unchosen, financial pressure. The dishonoring path isn’t asking for help. It’s silence, avoidance, or dishonesty about what you can actually pay. Bringing the difficulty into the light, rather than hiding from it, is itself an act of the same integrity Scripture asks of every debt, however it eventually gets resolved.

    This content is for educational purposes only and is not personalized financial, legal, or medical billing advice. Consider speaking with a hospital financial counselor or a nonprofit credit counseling service about your specific situation. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • The Vanderbilts: How a Fortune Can Disappear While No One’s Watching

    The Vanderbilts: How a Fortune Can Disappear While No One’s Watching

    By 1973, roughly 120 descendants of Cornelius Vanderbilt gathered at the university their ancestor had endowed a century earlier. Not one of them was a millionaire. That fact gets repeated often, and it’s real, worth taking seriously rather than explaining away. But it’s also not the whole truth about what the Vanderbilts actually left behind, and both things need to be said honestly, side by side.

    A crowd of modestly dressed 1970s descendants gathered before Vanderbilt University's grand columned facade

    What’s True: One Generation Really Can Undo Everything

    The Commodore built the largest fortune in American history. William nearly doubled it. Within a few generations after that, it was functionally gone. That’s not a myth or an exaggeration, it’s a documented outcome, and it should genuinely unsettle anyone who assumes a large enough fortune is automatically safe from this. It isn’t. Scale doesn’t protect against this pattern. It just takes longer to run out.

    What’s Also True: The Legacy Isn’t Reducible to a Bank Balance

    Grand Central Terminal still operates. Vanderbilt University still exists, and still bears the name of a man who never set foot on its campus. Biltmore, the one piece of the physical estate still standing under family-adjacent management, generates over $250 million a year today. None of that shows up in a simple statement like “the money ran out.”

    The Real Warning, Which Is the Part Worth Sitting With

    Here’s what actually made the decline dangerous, and it’s not what the popular version of the story usually emphasizes. It wasn’t one catastrophic decision. It was ordinary, habitual spending that nobody treated as urgent until the math had already stopped working.

    A butler dusting a marble mantelpiece in a visibly aging mansion room with faded wallpaper and worn furniture

    Mansions kept getting maintained. Balls kept getting thrown. Lifestyles kept getting sustained, on the assumption that they always had been and therefore always would be. The danger was never a single bad call. It was the absence of anyone asking the hard question early enough for the answer to still matter.

    A Biblical Pattern With the Same Shape

    Judges 2:10 describes something structurally similar, on a much larger scale: “After that whole generation had been gathered to their ancestors, another generation grew up who knew neither the Lord nor what he had done for Israel.” (NIV) This wasn’t a generation that deliberately rejected what came before them. They simply never really knew it, the way anyone truly knows something they had to fight for themselves. The Vanderbilt heirs born into palaces never had to build one.

    Where This Leaves You

    A family, or an individual, can absolutely lose in one generation what took several to build, and pretending otherwise is its own kind of denial. But the deeper lesson isn’t really about the money at all. It’s about whether the next generation actually understands what built it, and whether anyone is willing to ask the uncomfortable question before the math makes the answer unavoidable.

    📖 Want the full story? Get The Vanderbilts: Empire, Excess, Loss, and Redemption — the complete ebook.

    This content is for educational purposes only and is not personalized financial advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    This post is part of our ongoing look at lessons from the Vanderbilt series. Start the full story from the beginning here.

  • Is the Prosperity Gospel Biblical?

    Is the Prosperity Gospel Biblical?

    No, the prosperity gospel is not biblical. The core claim, that sufficient faith guarantees material wealth and physical health, does not hold up against the consistent witness of Scripture, including the actual lives of the apostles who wrote much of the New Testament. This is a different question than whether being rich is itself a sin, though the two are closely related.

    What the Prosperity Gospel Actually Teaches

    At its core, prosperity theology teaches that God wants every believer wealthy and healthy, and that poverty or sickness reflects insufficient faith or unconfessed sin. Giving, in this framework, is often presented as a kind of financial seed that guarantees a proportional return from God.

    Where It Breaks Down

    The apostle Paul, who wrote a significant portion of the New Testament, directly contradicts this framework in his own testimony. 2 Corinthians 11:27 describes his life as one of “labor and hardship… often without food… cold and naked.” Philippians 4:12 has him saying he has “learned the secret of being content in any and every situation, whether well fed or hungry, whether living in plenty or in want.” This wasn’t a man lacking faith. It was one of the most faithful men in Christian history, describing genuine material hardship as part of a life fully surrendered to God, not evidence against it.

    What Scripture Actually Promises

    Scripture promises God’s presence, provision for genuine need, and eternal reward, not a guarantee of earthly wealth in exchange for faith or giving. James 1:2-4 even frames trials as something to consider “pure joy,” producing perseverance, a framework entirely incompatible with the idea that hardship signals failed faith.

    Where This Leaves You

    Wanting financial stability isn’t wrong, and God does care about provision. But the specific claim that faith functions as a formula guaranteeing wealth doesn’t match Scripture’s own honest account of what faithful lives, including the apostle Paul’s, actually looked like.

    This content is for educational purposes only and is not personalized financial advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading