Tag: biblical finance

  • 7 Reasons Churches Need to Preach More on Tithing

    7 Reasons Churches Need to Preach More on Tithing

    There’s a strange gap sitting in the data on American church giving. Most churchgoers still believe tithing matters. Very few actually practice it. That gap is worth taking seriously, and it points less to a generosity problem than a teaching one.

    Illustration of a pastor preaching to an attentive congregation in a warmly lit church

    The Belief-Practice Gap, in Numbers

    According to research compiled by Fellowship Development, 77% of American Protestant churchgoers affirm that tithing is a biblical command that still applies today, down slightly from 83% in 2017. And yet only about 27% of churchgoers actually tithe at or above the traditional 10% mark. Average giving across all churchgoers sits at roughly 2.5% of net income, according to Christianity Today, actually lower than the 3.3% Christians gave during the Great Depression, a season with far less financial margin than most churchgoers have today.

    Illustration of a crowd split by a widening crack, labeled believe it and practice it, showing the gap between belief and action

    That’s not a small gap. Most people in the pews believe the teaching. Most aren’t living it out. Here are seven reasons that gap is worth churches addressing directly, not avoiding.

    1. Belief Without Practice Isn’t Discipleship

    A congregation that intellectually agrees tithing matters but doesn’t practice it hasn’t actually been discipled on the subject, it’s been informed about it. Those are different outcomes, and only one of them is the actual goal.

    2. Money Is One of the Most-Discussed Topics in Scripture

    Jesus talked about money and possessions more than almost any other single topic, more than heaven, more than prayer. A church that teaches deeply on prayer and heaven but avoids money isn’t giving a full picture of what Jesus actually emphasized.

    3. Silence Gets Filled By Something Else

    When churches don’t teach clearly on money, culture fills the gap instead, consumerism, financial anxiety, or vague guilt untethered from any actual biblical framework. Clear teaching is the alternative to that vacuum, not an intrusion into it.

    4. Generosity Is Linked to Real Wellbeing

    Research on giving and happiness, including studies published in the journal Science, has found that people who give measurably report greater happiness than those who don’t, a finding that holds across income levels. Teaching people to give isn’t just a church funding strategy, it’s pointing them toward something that appears to genuinely benefit them.

    5. Many Churchgoers Genuinely Don’t Know Where to Start

    Gross or net income, tithing while carrying debt, whether giving has to go to a local church specifically, these are common, sincere questions, and silence from the pulpit leaves people guessing rather than confidently obeying something they already believe in.

    6. Avoiding the Topic Often Comes From Fear, Not Wisdom

    Many pastors avoid teaching on money specifically to not be seen as chasing donations, an understandable instinct given how the topic has been abused elsewhere. But avoiding a true, important subject to dodge a false accusation isn’t wisdom, it’s letting fear set the curriculum.

    7. The Ministry Impact Is Real

    One estimate from Health Research Funding suggests that if every American Christian tithed at 10%, churches and ministries would have an additional $139 billion available annually. Whatever a congregation believes about the specific percentage, undertaught generosity has a real, measurable cost to the ministries and people that consistent giving could otherwise support.

    What This Isn’t Saying

    This isn’t an argument for guilt-driven fundraising appeals or manipulative giving campaigns, and it isn’t taking a side on the specific tithing debates covered elsewhere on this site. It’s simply naming what the data already shows: a wide gap between what churchgoers believe about money and what they actually do with it, and that gap closes through clear, consistent, honest teaching, not through avoidance.

    This content is for educational purposes only and is not personalized financial or tax advice.

    References and Further Reading

  • What Is a Mutual Fund? A Beginner’s Guide

    What Is a Mutual Fund? A Beginner’s Guide

    This is the second piece in our Investing Fundamentals series. If an index fund is a basket of investments that just tracks the market, a mutual fund is that same basic idea with one key difference: a person is actively steering it.

    Comic book style illustration of a fund manager steering a ship loaded with a basket of company stocks through rough seas

    What a Mutual Fund Actually Is

    A mutual fund pools money from many investors, just like an index fund does, and uses it to buy a collection of stocks, bonds, or other assets. The difference is who’s making the decisions. A mutual fund is run by a professional fund manager, or a team of them, who actively research companies, pick which ones to buy, and decide when to sell, all with the goal of beating the market rather than simply matching it.

    That active decision-making is the entire sales pitch behind a mutual fund: pay for expertise, and that expertise should, in theory, outperform a fund that’s just passively tracking an index.

    The Real Cost of That Expertise

    Illustration of a toll road showing fees being taken from a cart along the way, compared to a fee-free road arriving with more treasure

    Here’s where the comparison to index funds gets concrete. According to Investment Company Institute data, the asset-weighted average expense ratio for actively managed mutual funds sits around 0.59% a year. Index equity mutual funds, by contrast, average around 0.05%, more than ten times cheaper.

    On a $100,000 investment, that’s the difference between paying about $590 a year and paying about $50. Over decades, and compounded, that gap doesn’t stay small. A Motley Fool illustration puts real numbers to it: $100,000 invested for 20 years at 8% annual growth with a 2% expense ratio grows to roughly $320,000. That same $100,000 at a slightly lower 7% return but a 0.40% expense ratio grows to roughly $360,000, a higher ending balance despite the lower raw return, purely because of the fee difference.

    Does the Extra Cost Pay Off?

    This is the real question, and it’s a genuinely debated one in the investing world, not a settled fact. The honest answer is that the majority of actively managed funds underperform their benchmark index over long time periods, a pattern well-documented across decades of industry research, though certainly not every fund, and not every year. Some active managers do beat the market, sometimes for years at a stretch. The difficulty is knowing in advance which ones will, and paying the higher fee the entire time you’re trying to find out.

    Why Someone Might Still Choose One

    Mutual funds aren’t without a real case for themselves. A skilled manager can make judgment calls an index simply can’t, avoiding a struggling company before a downturn, or moving into a sector before it takes off. Some specialized markets, less efficiently priced than a broad index like the S&P 500, may genuinely reward active management more than others. And some investors are simply more comfortable with a professional making the calls rather than a fund that has no ability to react to changing conditions at all.

    The Practical Takeaway

    Mutual funds and index funds aren’t opposites so much as two different bets. An index fund bets that low costs and broad diversification will win out over time. A mutual fund bets that expert judgment is worth paying more for. Neither bet is inherently wrong, but the fee difference is real, it’s measurable, and it compounds right alongside your returns, which makes it one of the most important numbers to actually look at before choosing between the two.

    The Investing Fundamentals Series

    This content is for educational purposes only and is not personalized financial or investment advice. Consider talking with a licensed financial professional before making investment decisions.

    References and Further Reading

  • The Vanderbilt Family Story

    In 1810, a sixteen-year-old boy named Cornelius Vanderbilt borrowed $100 from his mother and bought a small boat to ferry passengers around New York harbor. By the time he died sixty-seven years later, he was worth more in cash than the United States Treasury itself held at the time. This is the full story of what his family did with that fortune across four generations: how it was built, how it very nearly evaporated in some of the most extravagant spending America has ever witnessed, and how one branch of the family found an unlikely second life in the very house that almost ruined them.

    Part One: The Commodore

    Cornelius Vanderbilt was born in 1794 on Staten Island to a family of modest means, and he left formal schooling behind entirely by age eleven. What he lacked in education he made up for in relentless physical work and an instinct for undercutting competitors that would define his entire career. That first ferry, purchased with his mother’s $100 loan, grew into a fleet, then into a full-scale steamboat empire spanning the eastern seaboard and, eventually, routes to California and Central America during the Gold Rush years, when tens of thousands of prospectors needed fast, reliable transit and Vanderbilt built a route through Nicaragua that undercut every competitor’s price. Ecclesiastes 9:10 says, “Whatever your hand finds to do, do it with all your might.” Vanderbilt seems to have taken that literally for the better part of six decades.

    He earned the nickname “Commodore” through sheer dominance of the shipping trade, and he earned a reputation for ruthlessness alongside it. When business rivals tried to shut him out of that Nicaragua transit route he’d built, he is famously said to have written them a one-line threat: “You have undertaken to cheat me. I won’t sue you, for the law is too slow. I’ll ruin you.” He generally did, driving rate wars so aggressive that competing shipping lines regularly paid him simply to go away and stop undercutting them, a tactic that became almost as profitable as running the ships themselves.

    By his sixties, an age when most men of his era considered themselves retired, he made an audacious pivot, selling off his shipping interests entirely and throwing his fortune into something newer and far riskier: railroads. It worked, spectacularly. He consolidated smaller, competing lines into the New York Central Railroad, one of the most powerful rail networks in the country, and in 1871 opened Grand Central Depot in Manhattan, the direct ancestor of today’s Grand Central Terminal. By the time of his death in 1877, he had amassed roughly $100 million, an almost incomprehensible sum for the era, and one that made him, by some measures, wealthier in real terms than the federal government’s own cash reserves.

    The Erie War

    Vanderbilt’s railroad ambitions produced one of the wildest corporate battles in American history: the fight for control of the Erie Railroad in 1868. Vanderbilt tried to acquire the Erie the same way he’d acquired everything else, buying up stock until he controlled it. His opponents, a trio of financiers named Daniel Drew, Jim Fisk, and Jay Gould, responded by doing something almost unthinkable: they simply printed more stock. Erie’s board controlled the company’s own printing press, and every time Vanderbilt bought up enough shares to gain control, Drew, Fisk, and Gould issued tens of thousands of new, freshly printed shares to dilute his position, flooding the market faster than Vanderbilt could buy. Vanderbilt reportedly spent more than $7 million trying to corner a stock that kept multiplying beneath him.

    When a New York judge, at Vanderbilt’s request, ordered Drew, Fisk, and Gould arrested for contempt of court over the scheme, the three men famously fled across the Hudson River to New Jersey with the company’s cash reserves stuffed into suitcases, setting up a temporary headquarters in a hotel in Jersey City, just outside the reach of New York law enforcement, where they continued running the company by proxy for months. Vanderbilt eventually cut his losses and settled, walking away from the fight with a real financial loss but an even more valuable lesson: even the shrewdest operator in America could be beaten at his own game by men willing to print their way out of a corner.

    But even at the height of his power, a much younger and far less famous man was quietly building something that would eventually test his empire in an entirely different way. John D. Rockefeller started small in the 1860s, one refinery among dozens in Cleveland, Ohio. By 1872, he had begun aggressively consolidating the oil refining business under Standard Oil, buying out 22 of Cleveland’s 26 refineries in a matter of weeks. That same year, Rockefeller and a group of refiners and railroad men formed the South Improvement Company, a scheme to secure secret rebates on oil shipments in exchange for guaranteed freight volume. The railroads at the table included Vanderbilt’s own New York Central, by then increasingly run day to day by his son, William Henry Vanderbilt, as the aging Commodore’s health declined. The scheme leaked to the press and collapsed under public backlash within weeks, but it revealed something important: the era of the unchallenged railroad titan was already ending, and a new kind of industrial power was rising fast enough to test even Vanderbilt’s empire.

    The Final Gift and a Contentious Death

    Vanderbilt’s one major act of public philanthropy came near the very end of his life. In 1873, persuaded largely by a Methodist bishop who saw an opportunity to unite a fractured post-Civil War nation through education, the Commodore gave $1 million to establish a university in Nashville, Tennessee, a place he had never visited and had no personal connection to. The school was renamed Vanderbilt University in his honor. It would remain, for the rest of his life, essentially his only large-scale charitable act, a single moment of institutional generosity from a man otherwise defined by decades of relentless, self-interested accumulation.

    When Vanderbilt died in January 1877, his death set off one of the most contentious inheritance disputes of the century, a preview of exactly the kind of family conflict that would define the generations to come, and the first real test of whether the fortune he’d spent sixty-seven years building could survive contact with his heirs.

    Part Two: The Son Who Doubled It (And the Con That Almost Caught Him)

    William Henry Vanderbilt was not, at first, anyone’s idea of a worthy heir. Known to the family as Billy, he struggled early in life and reportedly suffered a nervous breakdown as a young man. The Commodore, unimpressed, started him at 19 as a bank clerk rather than anywhere near the family business. What changed his father’s mind was a test, not a promotion: William was handed the small, failing Staten Island Railway, and he turned it around. That success earned him the presidency of the line in 1862, then steadily more responsibility over the following two decades, working his way up through the Hudson River Railroad and eventually into daily operational control of the New York Central itself, quietly running the empire for years before his father’s death made it official.

    A Bitter Will Contest

    When Cornelius Vanderbilt died in 1877, he left roughly 95% of his $105 million estate to William and William’s own sons, an extraordinarily concentrated decision for the era, when dividing an estate evenly among all children was the more typical approach. His other children, several daughters and a troubled son named Cornelius Jeremiah, who struggled with gambling debts his entire adult life, received far smaller sums. Cornelius Jeremiah, feeling cut out entirely despite bearing his father’s name, formally contested the will in court, arguing his father had been manipulated by William and was not of sound mind at the time of signing. The trial became a genuine public spectacle, dragging on for the better part of a year with testimony from mediums, family friends, and business associates all weighing in on the Commodore’s mental state in his final years. William ultimately settled with several of his siblings directly rather than risk a jury verdict, paying substantial additional sums to end the litigation and preserve both the estate and whatever remained of the family’s public image.

    According to William’s family biographer, Arthur T. Vanderbilt II, the Commodore’s parting words to him were blunt: any fool can make a fortune, it takes a man of brains to hold onto it. Proverbs 20:21 offers a matching warning from the other direction: “An inheritance claimed too soon will not be blessed at the end.” The Commodore’s insistence on testing William first, rather than simply handing him the keys decades earlier, reads like an instinctive understanding of exactly that principle, and the will contest that followed his death is a real-world illustration of what happens when that principle gets ignored by everyone else in the family.

    William more than justified the trust his father placed in him, at least financially. He aggressively expanded the family’s rail network, acquiring controlling interests in the Michigan Central, the Lake Shore and Michigan Southern, and the Canada Southern railways, among others, and pushed the family’s stake in the New York Central itself to roughly 87%. By the time poor health forced his retirement from railroad leadership in 1883, he had very nearly doubled his father’s fortune. Estimates of his estate at his death in 1885 range from $200 million to $232 million, making him, by some measures, briefly the richest man in the world.

    He was not universally beloved for it. In an 1882 newspaper interview, William was widely quoted responding to a question about an unprofitable train service he’d cancelled with the dismissive line, “The public be damned.” Whether he meant it quite as coldly as it read in print has been debated by historians ever since, but the phrase followed him for the rest of his life and became a kind of shorthand for Gilded Age indifference to public opinion, printed and reprinted in newspapers hostile to the railroad barons for decades afterward.

    Outfoxed by a President’s Son

    His business instincts were not infallible either, and one episode deserves telling in full. In 1884, William invested in Grant and Ward, a Wall Street banking firm whose partners included Ulysses S. Grant Jr., son of the former president and Civil War general. The firm’s other partner, Ferdinand Ward, nicknamed “the Young Napoleon of Finance” in the press for his seemingly magical investment returns, was in reality running what amounted to a Ponzi scheme, using new investors’ money to pay off earlier ones while quietly siphoning funds for himself. The firm’s apparent success, and the credibility lent by Grant’s own name attached to it, drew in investor after investor, including some of the most experienced financial minds in the country.

    Grant and Ward collapsed in May 1884, one of the most notorious financial scandals of the era. It didn’t just cost investors money, it completely wiped out former President Grant’s personal fortune. Grant, already dying of throat cancer, spent his final months racing to write his memoirs specifically to leave his family something to live on, a project he finished mere days before his death in 1885, and which went on to become one of the best-selling military memoirs in American history, largely because Mark Twain personally arranged its publication to help the Grant family recover financially. William Henry Vanderbilt, one of the shrewdest businessmen in the country, lost $150,000 in the same collapse, the son of a former president having personally lent his name and credibility to the very scheme that ruined him. Even a fortune built on genuine business skill offered no immunity to a well-dressed con wearing a famous name.

    William also expanded the family’s philanthropic footprint modestly beyond his father’s single gift, contributing to Columbia College’s School of Physicians and Surgeons among other causes, though giving remained a minor thread in his life compared to building the fortune itself. He built the first of what would become a long line of Vanderbilt mansions on Fifth Avenue, a limestone “triple palace” at 640 Fifth Avenue that set a new standard for the family’s public displays of wealth. And near the end of his life, he said something worth sitting with: inherited wealth, he confessed, was a real handicap to happiness, leaving him with nothing left to hope for or strive toward. He had eight children, every one of them growing up watching a fortune that had just doubled, in a family that had just built its first Fifth Avenue palace, with a father who privately wondered whether the money itself was good for anyone.

    Part Three: The Excess, By the Numbers

    What William’s children did with that fortune is where the story turns. Unlike his father’s concentrated inheritance strategy, William split his estate more evenly among his heirs, and the family’s competitive energy shifted almost entirely from railroads to real estate and social spectacle. 1 Timothy 6:9-10 warns that “those who want to get rich fall into temptation and a trap and into many foolish and harmful desires… the love of money is a root of all kinds of evil.” The next generation of Vanderbilts illustrated the warning almost too literally.

    The Ball That Bought Social Acceptance

    William Kissam Vanderbilt and his wife Alva built a 150-room limestone “chateau” at 660 Fifth Avenue, explicitly designed to force New York’s old-money establishment, who had always looked down on the Vanderbilts as vulgar new money despite their fortune, to finally accept the family socially. On March 26, 1883, Alva hosted a costume ball there for 1,200 guests, an event costing an estimated $6 million by today’s standards and one The New York World called “never equalled in the social history of the city.” Guests arrived dressed as royalty, historical figures, and mythological characters, and police held back crowds simply to watch the carriages arrive.

    The strategy worked exactly as intended: Mrs. Astor herself, the reigning gatekeeper of old New York society who had spent years refusing to acknowledge the Vanderbilts as social equals, was forced to pay a formal visit to Alva just to secure a ball invitation for her own daughter, effectively admitting the Vanderbilts into the highest tier of society at last. It is difficult to overstate how significant this was in Gilded Age New York: an entire evening of costumed spectacle had done more to legitimize the family socially than three generations of railroad and shipping wealth had managed on its own.

    Marble Cottages and Ruined Marriages

    Alva didn’t stop there. She and William Kissam went on to build Marble House in Newport, Rhode Island, a 50-room summer “cottage” that employed a staff of 36 and cost roughly $11 million to build at the time, an amount worth close to $300 million today. Cornelius Vanderbilt II built The Breakers, another Newport palace, just down the same stretch of coastline. Along Fifth Avenue itself, so many Vanderbilt mansions went up in succession that the block became known simply as “Vanderbilt Row.”

    The same ambition that built these houses shaped the family’s next generation in far more painful ways. Alva and William Kissam’s daughter, Consuelo Vanderbilt, was secretly engaged at 18 to a fellow American, Winthrop Rutherfurd, a match Alva considered beneath the family’s new social ambitions. Alva wanted a title, and she had her sights set on Charles Spencer-Churchill, the 9th Duke of Marlborough, whose family estate, Blenheim Palace in England, was in serious financial trouble and desperately needed an infusion of American money. According to multiple historical accounts, when Consuelo resisted, Alva locked her in her room, threatened to have Rutherfurd killed, and eventually claimed she was so ill with heart trouble over her daughter’s defiance that she was near death. Consuelo, only 18, gave in. She reportedly wept visibly at her own wedding in 1895, unable to hide her distress even in front of the assembled guests.

    Decades later, testifying in the couple’s eventual annulment proceedings, Alva stated it plainly under oath: “I forced my daughter to marry the Duke. I have always had absolute power over my daughter.” The marriage brought the Duke a dowry worth an estimated $2.5 million in railroad stock, enough to save Blenheim Palace from financial ruin, and it brought Consuelo eleven years of what she later described as a cold, loveless marriage before the couple separated, divorced, and eventually had the union annulled entirely, a process that required Alva’s own sworn testimony admitting the coercion in order to satisfy the Catholic Church’s grounds for annulment. Consuelo found genuine happiness only in a second marriage, years later, to a man she’d actually chosen herself.

    The Empire Runs Out

    The pattern repeated across the family for roughly two generations: each new house built partly to outdo the last one, each marriage increasingly treated as a strategic transaction, each fortune divided into more pieces than the one before, spread across heirs raised to display wealth more than to build it. The railroad empire that had generated the money in the first place didn’t survive its heirs either. New York Central, once one of the largest railroads in the country, declared bankruptcy in 1970. By 1947, every Vanderbilt mansion on Fifth Avenue had been demolished, their contents auctioned to help cover debts.

    In 1973, roughly 120 descendants of Cornelius Vanderbilt gathered at Vanderbilt University, the school the Commodore himself had endowed exactly a century earlier. According to family historian Arthur T. Vanderbilt II’s research, not one person in that room was a millionaire. A fortune once larger than the U.S. Treasury had, across four generations, simply run out, spent on houses that no longer stand, marriages contracted for status rather than affection, and a lifestyle that consumed far more than it ever generated.

    One branch of that same family tree is still publicly recognizable today. Gloria Vanderbilt, the fashion designer and “poor little rich girl” of Depression-era headlines, was the great-great-granddaughter of Cornelius Vanderbilt II, William Henry’s son, through her father Reginald Claypoole Vanderbilt. Her son, journalist Anderson Cooper, is therefore a great-great-great-grandson of the original Commodore, sitting on an entirely different branch of the family tree than the one this story turns to next, a branch that took a very different path.

    Part Four: The Biltmore Gamble

    While most of William Henry Vanderbilt’s children were competing to out-build each other in Newport and Manhattan, his youngest son took the same instinct somewhere no one else had: the mountains of North Carolina. George Washington Vanderbilt II began buying land near Asheville in 1888, eventually acquiring roughly 125,000 acres, and in 1889 broke ground on a house unlike anything else in America. He hired Frederick Law Olmsted, the same landscape architect behind New York’s Central Park, to design the grounds, a decision that shaped not just Biltmore’s gardens but eventually the entire discipline of American forestry, since Olmsted’s team pioneered scientific forest management on the estate’s surrounding acreage, techniques that spread across the country in the decades that followed.

    Building the Largest House in America

    Biltmore House took six years and the labor of more than 1,000 workers and 60 stonemasons to complete. A three-mile private railway spur was built just to haul materials to the site, along with an on-site brick kiln producing 32,000 bricks a day and a dedicated woodworking factory to supply finished materials for the interior. When it opened on Christmas Eve, 1895, the finished house held 250 rooms across nearly 179,000 square feet of floor space, 35 bedrooms, 43 bathrooms, 65 fireplaces, and three kitchens, along with an indoor swimming pool, a bowling alley, and a library holding more than 10,000 volumes, outfitted with technology most Americans had never seen in a private home: electric lighting, elevators, central heating, and indoor plumbing with hot running water. Running the house and stables required a domestic staff of roughly 80 people, a mix of local North Carolinians and specialists brought in from Europe, including an English head housekeeper and a French chef. Total construction cost was around $6 million in 1895 dollars, somewhere north of $180 million today.

    It was, in plain financial terms, an enormous gamble, and George Vanderbilt did not have a railroad network or a Standard Oil generating fresh income behind it, just the finite fortune he had inherited. When he died suddenly in 1914 at age 51, his widow Edith found herself managing an estate the family could no longer comfortably afford, eventually selling 87,000 acres of the surrounding land to the U.S. Forest Service, land that today forms part of Pisgah National Forest, simply to keep the core estate financially viable. Edith went on to become a respected civic figure in her own right, helping found what became the Asheville Chamber of Commerce and remaining active in the community for decades after her husband’s death, a very different legacy than most of her Vanderbilt in-laws pursued.

    A Secret Wartime Vault

    In 1930, hoping to generate revenue during the Great Depression, the family opened Biltmore House to public tours for the first time. It didn’t work, at least not for decades. By 1960, the house was losing roughly $250,000 a year. In between those two facts sits one of the strangest chapters in the estate’s history: in January 1942, weeks after Pearl Harbor, the National Gallery of Art in Washington, D.C. quietly evacuated 62 paintings and 17 sculptures, including works by Rembrandt, Raphael, Botticelli, and Gilbert Stuart’s famous portrait of George Washington, to Biltmore’s unfinished Music Room, fearing a Nazi air raid on the capital.

    The room was fitted with hidden steel vault doors concealed behind ordinary draperies, along with fire alarms and steel racks to hang the artwork properly. The priceless collection sat under 24-hour armed guard for nearly three years while ordinary tourists walked past the wall, never knowing that some of the most valuable paintings in the country were a few feet away. The art was quietly returned to Washington in the fall of 1944, well after the danger of invasion had passed, and the full story wasn’t publicly told for years afterward. For a house built to display one family’s wealth, it spent one of its most consequential chapters quietly protecting a piece of the nation’s cultural inheritance instead.

    Eight Years to $16.24

    The financial rescue came from a different Vanderbilt entirely. George Vanderbilt’s grandson, William A.V. Cecil, left a finance career at Chase Manhattan Bank in New York and returned to Asheville in 1960 to try to save the family home. Using a banker’s marketing instincts rather than nostalgia alone, including an eight-page newspaper advertisement and a small paid recipe card that drew a flood of mail orders from across the country, he spent eight years slowly turning the operation around, testing new ideas, cutting costs where he could, and treating the house less like a museum and more like a business that needed to earn its keep. In 1968, Biltmore recorded its first-ever profit: $16.24.

    From that almost absurdly small starting point, the estate has grown into something the original builder likely never imagined. Under Cecil’s continued leadership and later his son Bill Cecil Jr., the estate added a working winery in 1985, then hotels, restaurants, and an expanding events and licensing business that now sells Biltmore-branded furniture and home goods nationally. Today, Biltmore draws an estimated 1.4 million visitors a year, employs thousands of people, and generates annual revenue now estimated at roughly $258 million, an extraordinary turnaround for a house that was hemorrhaging money just decades ago. Buncombe County tax records place the estate’s overall value at hundreds of millions of dollars, and the Vanderbilt-Cecil family is now preparing a fifth generation of descendants, Bill Cecil Jr.’s own children, to eventually lead the business.

    What the Whole Story Actually Says

    Read start to finish, the Vanderbilt story is really two stories layered on top of each other. The first is about building: a ferry boy’s discipline compounding into the largest fortune in American history, surviving a stock-printing war with three of the shrewdest operators on Wall Street, then, remarkably, doubling again in the hands of a son nobody initially trusted, a son who survived being personally conned by a president’s own son and still nearly doubled what his father left him.

    The second story is about what happens next, when wealth meets generations that inherited the money without inheriting the discipline that built it, generations that spent fortunes on houses built purely to impress, and in Consuelo’s case, sacrificed a daughter’s own happiness for the sake of a title. Psalm 49:16-17 speaks directly into that gap: “Do not be overawed when others grow rich, when the splendor of their houses increases; for they will take nothing with them when they die, their splendor will not descend with them.” The Vanderbilts built some of the most splendid houses America has ever seen, and within a few generations, nearly all of that splendor, along with the money behind it, was gone.

    Except, remarkably, for one house. Proverbs 27:24 says plainly that “riches do not endure forever.” Biltmore very nearly proved that verse right, bleeding money for six decades after its builder’s death, even while secretly guarding some of the nation’s greatest treasures during its darkest financial years. What makes it worth telling as its own chapter is that it didn’t stay that way. It took one grandson’s willingness to leave a stable career, run the numbers honestly, and rebuild something sustainable, not from a lucky break, but from eight years of unglamorous, patient work. The same qualities that built the original fortune three generations earlier, discipline, patience, and a willingness to bet on something risky, resurfaced just in time to save the one piece of it still standing.

    This content is for educational purposes only and is not personalized financial, legal, or tax advice. All facts in this article are drawn from publicly available sources cited below; no claims are made beyond what those sources document.

    📖 Want the full story with more detail and illustrations? Get The Vanderbilts: Empire, Excess, Loss, and Redemption — the complete ebook.

    References and Further Reading

  • The Forgotten Vanderbilt: Did He Save the Fortune, or Destroy It?

    The Forgotten Vanderbilt: Did He Save the Fortune, or Destroy It?

    This is the second piece in our Vanderbilt series. Our first article ended with a young John D. Rockefeller quietly testing the limits of the Vanderbilt railroad empire in 1872, a scheme that collapsed under public backlash before it could do real damage. What that story didn’t get to: the man actually running New York Central by then wasn’t the aging Commodore. It was his son, William Henry Vanderbilt, and Rockefeller was about to become a permanent fixture in his career, sometimes as a rival, and just as often, surprisingly, as a partner.

    Illustrated portrait of William Henry Vanderbilt standing before a Chateauesque railroad terminal in Gilded Age style

    The Son Nobody Expected Much From

    Cornelius Vanderbilt did not initially see a successor in his eldest son. William, known to the family as Billy, struggled early on and reportedly suffered a nervous breakdown as a young man. The Commodore, unimpressed, started him at 19 as a bank clerk rather than anywhere near the family business.

    What changed his father’s mind was a test, not a promotion. William was put in charge of the small, failing Staten Island Railway, and he turned it around. That success earned him the presidency of the Staten Island line in 1862, then the vice presidency of the Hudson River Railroad, then of the New York Central itself by 1869. By the time the Commodore died in 1877, William had spent nearly two decades quietly proving himself before he ever controlled the whole empire.

    A Deliberate, Concentrated Inheritance

    When Cornelius Vanderbilt died, he left roughly 95% of his $105 million estate to William and William’s own sons, an extraordinarily concentrated decision at a time when dividing an estate evenly among all children was the more typical approach. His other children received far smaller sums; his daughters $200,000 each, and his troubled son Cornelius Jeremiah, considered untrustworthy with money, received $300,000. According to William’s family biographer, Arthur T. Vanderbilt II, the Commodore’s parting words to William were blunt: any fool can make a fortune, it takes a man of brains to hold onto it.

    The concentrated inheritance didn’t go unchallenged. Several of William’s siblings sued for a larger share. Rather than fight it out in public, William settled, paying each sister an additional $500,000 and reaching a similar arrangement with his brother. It resolved the dispute, and it’s worth noting as its own small lesson: even a carefully planned succession created real family conflict, and William’s response was to spend money proactively to preserve peace rather than let resentment sit unresolved.

    Doubling an Already Enormous Fortune

    What William did next answered any remaining doubts. He expanded the New York Central network aggressively, acquiring the Chicago and North Western Railway, the Nickel Plate Railroad, and the Lake Shore and Michigan Southern, among others, while the family’s stake in New York Central itself reached roughly 87%. By the time poor health forced his retirement from railroad leadership in 1883, William had very nearly doubled his father’s fortune. Estimates of his estate at his death in 1885 range from about $200 million to $232 million, making him, by some measures, the richest man in the world at the time.

    Rockefeller: Rival and, Just as Often, Ally

    Here’s where the record gets more interesting than a simple story of William getting outmaneuvered. Historical accounts, including Ida Tarbell’s contemporaneous history of Standard Oil, document that William H. Vanderbilt himself became a stockholder in Rockefeller’s Standard Oil Company by 1876. And in 1877, when the Pennsylvania Railroad’s Empire Transportation subsidiary tried to move into oil refining, directly threatening Rockefeller’s business, it was Vanderbilt’s New York Central that Rockefeller leaned on as an ally against the Pennsylvania line, not the other way around.

    The two men remained locked in genuine competition over freight rates for years. But the relationship was never simply predator and prey. William learned to be a stockholder, a competitor, and a strategic partner with the same man, sometimes all at once, which is arguably a more useful lesson than a straightforward story of getting outfoxed would have been.

    What This Succession Actually Teaches

    A few real lessons sit inside this story. First, the Commodore didn’t hand William the empire, he tested him with something small and failing first, and only trusted him with more once he’d proven himself. Luke 16:10 puts the same principle plainly: “Whoever can be trusted with very little can also be trusted with much, and whoever is dishonest with very little will also be dishonest with much.” (NIV) The Commodore seems to have understood this instinctively, decades before it would have been quoted back at him. Second, concentrating the inheritance in the most capable heir, rather than splitting it evenly, was a deliberate strategy, one that came with real relational cost that had to be managed afterward, not ignored. Third, even William wasn’t immune to being fooled: in 1884, he lost $150,000 in the collapse of Grant and Ward, a Ponzi scheme run partly by Ulysses S. Grant’s own son. Brains and experience reduce risk. They don’t eliminate it.

    The Cracks Beginning to Show

    Illustrated Gilded Age street scene of the Vanderbilt Triple Palace mansion on Fifth Avenue with horse drawn carriages

    William built the first of what would become a long line of Vanderbilt mansions on Fifth Avenue, a limestone “triple palace” at 640 Fifth Avenue that set a new standard for the family’s public displays of wealth. He also, near the end of his life, said something worth sitting with: “Inherited wealth is a real handicap to happiness. It has left me with nothing to hope for, with nothing definite to seek or strive for.”

    He had eight children. Every one of them grew up watching a fortune that had just doubled, in a family that had just built its first Fifth Avenue palace, with a father who privately wondered whether the money itself was good for anyone. That tension, a fortune still growing, a family rapidly expanding, and a lifestyle standard climbing right alongside both, is exactly where the next chapter of this story begins.

    📖 Want the full story? Get The Vanderbilts: Empire, Excess, Loss, and Redemption — the complete ebook.

    The Full Vanderbilt Series

    Or see the full series hub page for the complete story, including practical lessons drawn from it.

    This content is for educational purposes only and is not personalized financial, legal, or tax advice. All facts in this article are drawn from publicly available sources cited below; no claims are made beyond what those sources document.

    References and Further Reading
  • The Widow’s Mite: Why Jesus Praised the Smallest Gift in the Temple

    The Widow’s Mite: Why Jesus Praised the Smallest Gift in the Temple

    Picture the scene: a busy temple courtyard, wealthy men in fine robes stepping forward one by one to drop large sums into the temple treasury, the clink of coins loud enough to turn heads. Then a poor widow steps up, and quietly drops in two small coins worth barely a fraction of a cent combined. Jesus, watching the whole thing, tells his disciples something that would have stopped them cold: she gave more than all the rest.

    Illustration of wealthy robed figures dropping large amounts of coin into an ornate ancient temple treasury box

    The Scene, in Detail

    The story appears in both Mark 12:41-44 and Luke 21:1-4. Jesus was sitting near the temple treasury, watching people put in their gifts, a public act in that era, since the treasury consisted of trumpet-shaped receptacles where coins were audibly dropped in. Many rich people, Mark tells us, put in large sums. Then one poor widow came and put in two small copper coins, worth together about a penny.

    Jesus called his disciples over specifically to make a point of it. “Truly I tell you,” he said, “this poor widow has put in more than all the others. They gave out of their abundance, but she, out of her poverty, put in everything she had, all she had to live on.” (NIV)

    What the Greek Reveals

    Two small details from the original language add real weight to this story. The coins she gave were called lepta (λεπτά), the smallest, lowest-value coin in circulation at the time, literally meaning “thin” or “small.” It was about as low as currency got.

    And the phrase “all she had to live on” translates the Greek word bios (βίος), which doesn’t simply mean money or savings. It means life itself, the same root behind our word “biology.” Mark isn’t just saying she gave her spare cash. The word choice says she gave her livelihood.

    Why This Isn’t About the Amount

    The math, on its face, doesn’t work in any normal accounting sense. Two small coins are not more than the large sums the wealthy donors gave, not by any measure of pure quantity. Jesus isn’t making a math argument. He’s redefining what generosity actually measures.

    The wealthy donors gave out of their abundance, meaning what they gave cost them nothing they’d actually feel. Their lifestyle didn’t change. Their security wasn’t touched. The widow gave everything she had left to live on, an act that put her next meal in question. Jesus measures the gift not by its size but by what it actually cost the giver.

    A Detail Easy to Miss

    Illustration of a poor widow dropping two small coins into the temple treasury as Jesus, depicted with authentic Middle Eastern features, and his disciples watch nearby

    It’s worth noticing that Jesus doesn’t tell the widow to stop, doesn’t intervene to suggest she’s being reckless with her last money, and doesn’t hold her up as someone who made a poor financial decision. He holds her up as the standard. This sits alongside other places in the Gospels where Jesus shows real concern for the poor and vulnerable, which makes his silence here notable. He doesn’t correct her. He commends her.

    That doesn’t mean this passage is a command for everyone to give away their entire livelihood. It’s describing what he saw in one specific act of worship, not laying out a universal financial strategy. But it does mean the passage can’t be softened into merely being about the size of a check.

    What This Actually Asks of Us

    If Jesus measures giving by cost rather than size, the practical question for anyone today isn’t how does my gift compare to what other people give. It’s did this actually require something from me. A wealthy person giving a large sum that doesn’t change their lifestyle at all isn’t automatically living out this passage just because the number looks generous. Someone giving a smaller amount that genuinely costs them something might be living it out more fully than they realize.

    This isn’t a passage designed to make anyone feel guilty about their income level or their capacity to give. It’s a reframe: the size of the number was never the point God was measuring. The heart behind it was.

    This content is for educational purposes only and is not personalized financial or tax advice. Scripture quotations taken from The Holy Bible, New International Version® NIV® Copyright © 1973, 1978, 1984, 2011 by Biblica, Inc.® Used by permission. All rights reserved worldwide.

    References and Further Reading

  • A Brief History of Tithing: What the Bible Actually Says

    A Brief History of Tithing: What the Bible Actually Says

    Ask ten Christians what tithing means and you’ll likely get ten different answers. Some will tell you it’s a strict 10% off the top, non-negotiable. Others will say it’s an Old Testament rule that doesn’t apply to New Testament believers at all. Both sides have real Scripture behind them. Here’s the actual history.

    Where Did Tithing Come From?

    Short answer: The first tithe in the Bible is in Genesis 14, when Abram (later Abraham) gave a tenth to Melchizedek, king of Salem and priest of God Most High. That was centuries before the Law of Moses. Later, the Law made the tithe a command for Israel: a tenth of crops and livestock to support the Levites, the temple and the poor (Leviticus 27:30-32, Numbers 18:21, Deuteronomy 14:28-29). Whether that command still binds Christians today is a real debate, and we lay out both sides below.

    Illustration of ancient Israelite figures in robes exchanging a tithe offering

    Where the Tithe Came From

    The tithe shows up early in the Old Testament, well before the Law of Moses. Abraham gave a tenth of the spoils of battle to Melchizedek, king of Salem and priest of God Most High, in Genesis 14. Jacob vowed a tenth of everything God gave him in Genesis 28. By the time of Moses, tithing had become codified law: Israelites were commanded to bring a tenth of their crops and livestock to support the Levites, the tribe set apart for the priesthood and temple service, since the Levites received no land inheritance of their own (Leviticus 27:30-32, Numbers 18:21).

    This wasn’t charity in the modern sense. It was closer to a national tax that funded Israel’s entire religious and social infrastructure, including provision for the poor, the foreigner, the widow, and the orphan (Deuteronomy 14:28-29).

    Did the Early Church Tithe?

    This is where it gets genuinely debated, and worth being honest about rather than picking a side and pretending it’s obvious. The New Testament never explicitly commands a 10% tithe for Christians. The early church in Acts didn’t run on a fixed percentage, it ran on radical, voluntary generosity, believers selling property and laying the proceeds at the apostles’ feet, giving as anyone had need (Acts 2:44-45, Acts 4:32-35).

    Paul’s instructions to the Corinthian church point the same direction. He tells believers to set aside a portion of their income “as he may prosper” (1 Corinthians 16:2), and later urges cheerful, willing giving rather than giving under compulsion or by a fixed rule (2 Corinthians 9:7). Some Christian scholars, including writers like Stuart Murray Williams, argue directly that the tithe was a Mosaic Law requirement never carried forward as binding on New Testament believers, replaced instead by proportional, Spirit-led generosity.

    Other traditions push back, pointing out that tithing predates the Law of Moses entirely (Abraham gave his tithe centuries before Sinai), and that Jesus himself affirmed tithing practice while criticizing those who tithed meticulously but neglected justice and mercy (Matthew 23:23), suggesting he saw it as a floor, not something to be abandoned.

    Same 10% for the Wealthy and the Poor?

    This is the practical question that matters most, and it’s worth sitting with rather than rushing past. A flat 10% is a very different sacrifice for someone earning $30,000 a year than for someone earning $3 million. Jesus made exactly this point when he watched a poor widow give two small coins at the temple, and told his disciples she had given more than all the wealthy donors combined, because she gave out of her poverty while they gave out of their abundance (Mark 12:41-44, Luke 21:1-4).

    That story doesn’t settle the tithing debate, but it does settle something else: God has never measured generosity by the size of the number. He measures it by what it actually costs the giver. Whatever position a Christian lands on regarding a fixed 10%, the widow’s example suggests the real question isn’t “did I hit the percentage,” but “did this giving actually require faith and sacrifice from me.” For a closer look at that exact debate, see our piece on whether the 10% tithe is a biblical command or a guideline.

    Where This Leaves Us

    Illustration of a family giving generously together, warm and heartfelt

    This site isn’t going to tell you which side of the tithing debate is correct, since faithful, Bible-believing Christians land in different places on this one. What we will say is this: whether you land on a strict 10%, a percentage that grows as you’re able, or Paul’s “as you have prospered” principle, the goal was never a number for its own sake. It was always a heart posture, that everything you have already belongs to God, and giving is simply putting that belief into practice. If you’re wondering why this topic doesn’t come up more often from the pulpit, we’ve written about that too: 7 reasons churches need to preach more on tithing.

    Frequently Asked Questions About the History of Tithing

    Who gave the first tithe in the Bible?

    Abram, later called Abraham. In Genesis 14:18-20 he gave Melchizedek, king of Salem and priest of God Most High, a tenth after a military victory. Hebrews 7 looks back on that same moment.

    Where is tithing first mentioned in Genesis?

    Twice. Genesis 14:20 records Abram’s tenth to Melchizedek. Genesis 28:22 records Jacob’s vow to give God a tenth of everything God gave him.

    Was tithing part of the Law of Moses?

    Yes. The Law commanded Israel to give a tenth of crops and livestock (Leviticus 27:30-32). It supported the Levites, who had no land of their own (Numbers 18:21), and helped care for foreigners, orphans and widows (Deuteronomy 14:28-29). But the practice is older than the Law, which is one reason Christians still debate whether it applies today.

    When did tithing become money?

    In ancient Israel, tithes were mostly crops and animals. Deuteronomy 14:24-26 let a family that lived too far from the place of worship sell its tithe for silver, carry the silver, and buy food there instead. Giving in coins and, later, paper money grew as economies moved from farming to wages. Many Christians today ask a related question: should you tithe on gross or net income?

    Did the early church tithe?

    The New Testament never sets a fixed percentage for Christians. The church in Acts gave freely and often far beyond 10%. See 3 incredible stories of generosity from early church history.

    This content is for educational purposes only and is not personalized financial, legal, or tax advice.

    References and Further Reading

  • 4 Reasons It’s Really All God’s

    4 Reasons It’s Really All God’s

    “It’s All God’s” isn’t just a name. It’s the whole premise this site is built on. Here are four real reasons that premise holds up, from history, from Scripture, and from actual science.

    Illustration of a person joyfully giving a gift to another person, with a warm golden glow

    1. Generosity Has Shaped Christianity Since Day One

    The very first Christians weren’t known for their doctrine statements or their buildings. They were known for how they shared. Acts 2:44-45 describes believers selling possessions and distributing to anyone who had need. It wasn’t a side detail, it was one of the first things outsiders noticed about this new movement. That reputation followed Christianity for centuries: writers like Justin Martyr and Tertullian describe organized giving to widows, orphans, and prisoners as a defining feature of Christian communities, not an occasional act of charity.

    2. Science Confirms Giving Makes Us Happier

    This isn’t just a nice sentiment, it’s been tested directly. A landmark 2008 study published in the journal Science, led by psychologist Elizabeth Dunn, found that people who spent money on others reported measurably greater happiness than people who spent the same amount on themselves, even when the amounts were small. Dunn’s broader research since then has found this effect holds true across income levels, and a follow-up study spanning 136 countries found the link between generosity and happiness holds up worldwide, not just in wealthy nations.

    3. Greed and Hoarding Are Linked to Real Psychological Harm

    Illustration of a person alone and isolated surrounded by piles of coins, representing the weight of hoarding

    The flip side is just as well documented. Psychologist Tim Kasser has spent decades studying materialism, the tendency to prioritize accumulating wealth and possessions above other values. A major meta-analysis he co-authored, pulling together data across cultures and measurement methods, found a consistent pattern: the more materialistic a person’s values, the more likely they were to report depression, anxiety, and even physical health complaints, regardless of age, income, or culture. Materialism doesn’t just fail to deliver happiness, it actively appears to work against it.

    4. Scripture Said This Before the Studies Did

    None of this would have surprised the writers of Scripture. Jesus said it plainly: it is more blessed to give than to receive (Acts 20:35). Proverbs 11:24-25 puts it almost like a paradox, one person gives freely and gains even more, another withholds what is right and comes to poverty, the generous soul will be enriched. Modern psychology spent decades and considerable research funding rediscovering something the Bible stated as simple fact thousands of years ago.

    The Point

    None of this means giving is a transaction, a formula where you give X and receive Y in personal happiness. That would miss the point entirely. It simply means that when Scripture says it’s all God’s, and calls us to hold our resources with open hands rather than closed fists, it isn’t asking us to sacrifice our wellbeing for someone else’s. The research suggests the opposite: open hands tend to be happier hands.

    This content is for educational purposes only and is not personalized financial or psychological advice. If you’re experiencing ongoing anxiety or depression, consider speaking with a licensed mental health professional.

    References and Further Reading
  • Carnegie vs. Rockefeller: How Their Rivalry Became a Race to Give It All Away

    Carnegie vs. Rockefeller: How Their Rivalry Became a Race to Give It All Away

    There’s a lot documented about the rivalry between Andrew Carnegie and John D. Rockefeller. Steel against oil. Two of the wealthiest men in American history, both accused in their own time of ruthless business tactics and monopolistic power. That part of the story has been told a thousand times.

    This isn’t that story. This is about what happened next, when the same competitive drive that built two empires turned toward giving those empires away.

    Vintage newspaper style cartoon illustration of John D Rockefeller and Andrew Carnegie facing each other, with Standard Oil derricks behind Rockefeller and steel mills behind Carnegie

    From Building Fortunes to Giving Them Away

    In 1901, Carnegie sold his steel company to J.P. Morgan for $480 million, roughly the equivalent of well over ten billion dollars today, and became, briefly, the richest man in the world. He didn’t stay that way on purpose. Over the rest of his life, Carnegie gave away more than $350 million, including some $56 million to build 2,509 public libraries around the world.

    Rockefeller, watching his rival give away a fortune, didn’t sit still. By the time he died in 1937, Rockefeller had given away more than $530 million. In 1919 alone, he made a single gift of $100 million, at the time the largest philanthropic gift in world history, split between the General Education Board and his own Rockefeller Foundation. That one gift alone equaled nearly 0.1 percent of the entire U.S. economy that year.

    Neither man was shy about the comparison. Rockefeller had openly cited Carnegie’s example as motivation for his own giving. What had once been a competition over market share in steel and oil became, in its final act, a competition over impact. And unlike almost every other rivalry in American business history, this one is remembered as a good thing, precisely because both men treated generosity as something to compete over.

    How We’re Still Feeling It Today

    This isn’t just history. The decisions these two men made with their fortunes are still shaping daily life in ways most people never connect back to them.

    Libraries

    Of Carnegie’s 2,509 libraries, around 1,679 were built in the United States, and a meaningful number are still operating as public libraries today. One of them has a story worth telling on its own.

    In 1905, an educator named Albert Meyzeek petitioned the city of Louisville, Kentucky, for a public library that African American residents could actually use, staffed by their own community, since Louisville’s library system excluded Black residents entirely at the time. The library opened that year in three rented rooms. In 1908, Carnegie’s library fund financed a permanent building at 10th and Chestnut Streets, still standing today as the Western Branch Library. Its first librarian, Thomas Fountain Blue, became the first African American in the nation to head a public library.

    Warm illustrated depiction of the historic Western Branch Library in Louisville Kentucky

    That building still serves its community more than a century later, a direct, physical result of one very wealthy man’s decision about what his fortune was for. But it almost didn’t make it that far. By 2001, the branch was facing closure, a casualty of budget cuts nearly a century after Carnegie’s money built it. That’s when Prince, the musician, made a quiet donation of $12,000 to keep it open, asking for no publicity in return. The branch survived. A library funded by one of the wealthiest men in American history was saved, decades later, by one of music’s most private acts of generosity.

    Healthcare

    Rockefeller’s giving reshaped American medicine at its foundation. His Sanitary Commission launched a campaign against hookworm disease across the American South, running public education efforts that reached more than 2 million people at over 25,000 public meetings. He funded the creation of the first schools of public health at Johns Hopkins and Harvard, and established what became Rockefeller University, one of the world’s leading centers of medical research to this day. The model of large-scale, foundation-funded medical research that Rockefeller pioneered is still how much of modern biomedical science gets funded.

    The Arts

    Carnegie’s name is still on one of the most famous concert venues in the world. Carnegie Hall, which he funded and opened in 1891 in New York City, remains one of the most prestigious performance venues on earth, still hosting concerts more than 130 years later. The Rockefeller family’s cultural footprint continued through the next generation as well, most notably in the development of Rockefeller Center and support for New York’s Museum of Modern Art, cultural landmarks that grew out of the same fortune and the same underlying instinct to put wealth toward something lasting.

    The Real Lesson in the Rivalry

    We tend to think of rivalries as something negative, two people or companies trying to tear each other down. Carnegie and Rockefeller’s story flips that. Their competition never stopped, it just changed direction, from who could out-earn the other to who could do the most good with what they’d earned. 1 Timothy 6:18 puts it simply: those who are rich in this present world are to do good, to be rich in good deeds, and to be generous and willing to share. Carnegie and Rockefeller, for all the criticism they earned building their fortunes, spent their final decades in a genuine contest to give those fortunes away. It’s one of the rare rivalries in history where everybody, including people not yet born when it started, ended up better off.

    📖 Now Available: The Full Book

    The Vanderbilts: Empire, Excess, Loss, and Redemption book cover

    If this rivalry between Gilded Age titans caught your attention, our new book traces another one of that era’s legendary families across four generations, illustrated, with practical lessons on stewardship in every chapter. Get The Vanderbilts: Empire, Excess, Loss, and Redemption as an ebook today.

    This content is for educational purposes only and is not personalized financial, legal, tax, or investment advice.

    References and Further Reading

  • I Don’t Have Enough Money to Budget, and 5 Other Lies About Budgeting

    I Don’t Have Enough Money to Budget, and 5 Other Lies About Budgeting

    “I don’t have enough money to budget” might be the most common excuse for not budgeting, and it has the logic exactly backwards. When money is tight is precisely when a budget matters most, not least. Here are six lies worth clearing up.

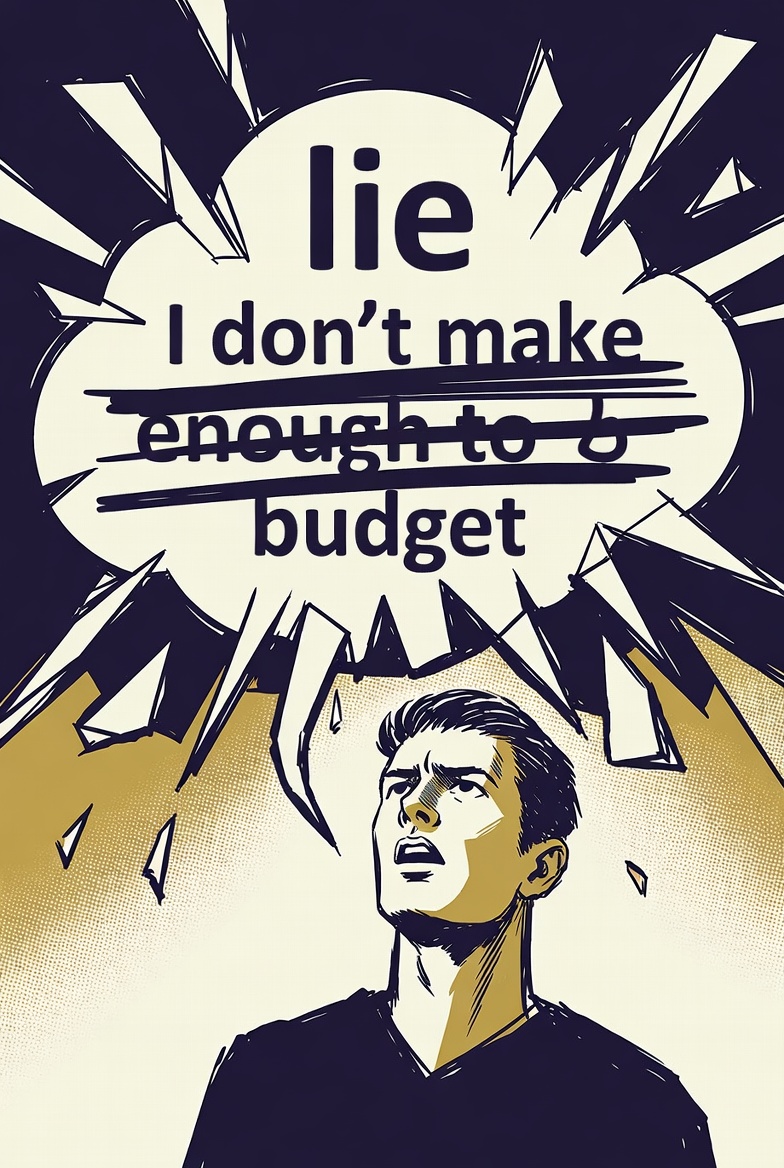
    Illustration of the budgeting myth I don't make enough to budget being torn away

    Lie 1: “I Don’t Make Enough Money to Budget”

    This gets it backwards. A budget isn’t a tool for people with money left over, it’s a tool for making sure every dollar has a job, and that matters more, not less, when there aren’t many dollars to go around. If you’re comfortably ahead each month, a wasted $30 barely registers. If you’re stretched thin, that same $30 might be the difference between covering gas for the week or not. The tighter the money, the more every single dollar needs a plan, which is exactly what a budget provides.

    Lie 2: “Budgeting Just Means Restriction”

    A budget isn’t a list of things you can’t have. It’s a plan for where your money goes before it’s already gone. That distinction matters more than it sounds. Deciding once that $100 goes toward entertainment this month means you’re not re-litigating that decision every single weekend. Psychologists call this decision fatigue, the well-documented tendency for the quality of our choices to decline the more decisions we’re forced to make in a day. A budget pre-makes dozens of small financial decisions in advance, freeing up mental energy for everything else in life.

    Lie 3: “I’ll Start Budgeting Once Things Calm Down”

    Things rarely calm down on their own. Waiting for a quieter season before building a plan usually means waiting indefinitely. The plan is what creates the calm, not the other way around.

    Lie 4: “Budgeting Is Just About the Math”

    The math matters, but it’s not the whole story. A 2023 American Psychological Association survey found that roughly 72% of Americans report money as a significant source of stress, and much of that stress comes from uncertainty, not knowing whether bills will be covered or an emergency will wreck the month. A budget’s real power is psychological as much as mathematical: it replaces uncertainty with a plan, and a plan, even an imperfect one, measurably reduces anxiety.

    Lie 5: “A Budget Has to Be Perfect to Work”

    A rough budget you actually follow beats a perfect spreadsheet you abandon after two weeks. Every category doesn’t need to be exact. It needs to exist, get reviewed, and get adjusted as real life happens.

    Lie 6: “Budgeting Means Doing It Alone and Never Talking About It”

    Research on financial disclosure has found that talking openly about money, including budgeting and spending, measurably reduces financial anxiety, largely because it restores a sense of control. Money kept secret tends to feel heavier than money talked about honestly, whether that’s with a spouse, a trusted friend, or in a church community that treats financial struggle with grace instead of judgment.

    Illustration of a person feeling calm and at ease, representing relief after budgeting

    The Real Starting Point

    Proverbs 27:23 offers surprisingly practical wisdom for something written thousands of years before spreadsheets: know well the condition of your flocks, and give attention to your herds. In modern terms, know what you actually have, and pay attention to it. That’s the entire starting point of a budget, nothing more complicated than that. Not perfection, not abundance, just honest attention to what’s actually there, and a plan for where it goes.

    This content is for educational purposes only and is not personalized financial advice.

    References and Further Reading

  • Commodore Vanderbilt: From Ferry Boy to Railroad Titan (And the Rival Who Challenged His Empire)

    Commodore Vanderbilt: From Ferry Boy to Railroad Titan (And the Rival Who Challenged His Empire)

    In 1810, a sixteen-year-old boy borrowed $100 from his mother and bought a small boat to ferry passengers and freight around New York harbor. By the time he died sixty-seven years later, that boy, Cornelius Vanderbilt, was the richest man in American history, worth more than the U.S. Treasury itself held in cash at the time.

    Illustration of a young Cornelius Vanderbilt as a teenage ferry boy on New York harbor

    From Ferries to an Empire

    Vanderbilt earned the nickname “Commodore” the hard way, building a shipping empire boat by boat, route by route, undercutting competitors and outworking nearly everyone in the business. By his 60s, when most men of his era were long retired, he made an audacious pivot: he sold off his shipping interests and threw his fortune into something newer and riskier, railroads.

    It worked. Vanderbilt consolidated smaller lines into the New York Central Railroad, one of the most powerful rail networks in the country, and in 1871 opened Grand Central Depot in Manhattan, the direct ancestor of today’s Grand Central Terminal. By the time of his death in 1877, he had amassed roughly $100 million, an almost incomprehensible fortune for the era.

    The Titan

    Illustration of an older, formally dressed man representing Cornelius Vanderbilt as a railroad titan

    By the early 1870s, Vanderbilt sat atop what looked like an unshakeable empire. But a much younger, far less famous man was quietly building something that would eventually test even a fortune as large as his.

    The Rival Nobody Saw Coming

    John D. Rockefeller started small in the 1860s, one refinery among dozens in Cleveland, Ohio. But by 1872 he had already begun aggressively consolidating the oil refining business under his company, Standard Oil, buying out 22 of Cleveland’s 26 refineries in a matter of weeks.

    That same year, Rockefeller and a group of refiners and railroad men formed the South Improvement Company, a scheme to secure secret rebates on oil shipments in exchange for guaranteed, high-volume freight business. The railroads at the table included the Erie, the Pennsylvania, and Vanderbilt’s own New York Central, by then increasingly run day to day by his son, William Henry Vanderbilt, as the aging Commodore’s health declined. The deal offered the railroads reliable volume and offered Rockefeller drastically lower shipping costs than his competitors could get, a real threat to the balance of power the railroads had grown used to controlling.

    The scheme leaked to the press within weeks and collapsed under public backlash before it could fully take hold. But it revealed something important: the era of the unchallenged railroad titan was already ending, and a new kind of industrial power, built on oil instead of iron rails, was rising fast enough to make even Vanderbilt’s empire take notice.

    What This Story Actually Teaches

    It’s tempting to read Vanderbilt’s story as simply a rags-to-riches tale, and it is one. But it’s also a reminder that no fortune, no matter how large, stays unchallenged forever. Vanderbilt himself proved that by displacing established shipping and rail interests on his way up. Within a generation of his death, a new kind of empire was already testing the limits of his family’s. Ecclesiastes 2:18-19 captures the tension well: the Preacher grieves that he must leave the fruit of his labor to someone who comes after him, and he has no idea whether that person will be wise or foolish with it. Vanderbilt built one of the largest fortunes the world had ever seen. What happened to it in the hands of the generations after him is a story worth telling on its own, and we will, starting with the son the Commodore almost didn’t trust with any of it, and the surprising, complicated relationship he’d go on to have with the very man who’d just tested his father’s empire.

    📖 Want the full story? Get The Vanderbilts: Empire, Excess, Loss, and Redemption — the complete ebook.

    The Full Vanderbilt Series

    Or see the full series hub page for the complete story, including practical lessons drawn from it.

    Lessons from the Commodore’s story: 5 Ways the Commodore’s Decision Protected the Family, Lifestyle Creep: The Real Lesson Hiding in the Vanderbilt Story, and What Is an Asset? And meet the man building a fortune in the same city at the same time: John Jacob Astor.

    This content is for educational purposes only and is not personalized financial, legal, tax, or investment advice.

    References and Further Reading